 odyvero

For three nights for two people in a four-star hotel in Barcelona, the tourist tax comes to €55.44 including the 10% hotel VAT, according to the rates in effect since April 2026. Apartments, hostels and accommodation in nearby towns are subject to different amounts. Here’s how to compare accommodation, calculate the children’s share and identify what you will actually still have to pay.
The cost per person and per stay
The surcharge sometimes appears only after the room price, in the booking conditions or at checkout. For a long weekend, however, it deserves its own line from the very first budget calculation. In Barcelona, the amount depends on the accommodation category and the number of taxable guests. A double room therefore generally accommodates two taxpayers, even when only one person pays the bill.
The Catalan tax on stays in tourist establishments includes a regional component, to which the city adds a surcharge. For the Barcelona accommodation rates shown here, the municipal component is €5 per person and stay unit. The two components are added together before the applicable VAT on the service is taken into account. Comparing only the regional amount with the total for another type of accommodation creates an artificial discrepancy.
The rates below apply from April 1, 2026, to March 31, 2027. They are therefore suitable for planning a stay in late 2026 or early 2027, subject to the special case of a booking fully prepaid together with its tax. A rate found in an old quote or an early-year guide may apply to a different period.
The initial calculation is simple: taxable guests × taxable stay units × rate for the establishment. For an ordinary hotel stay, the number of nights is a useful basis for this estimate. The tax rules refer more broadly to days or fractions of days, with or without an overnight stay; a particular day-use service should therefore be checked with the establishment. The seven-unit cap and exemptions are then handled for each person.
Rates by accommodation type
The table brings together the official rates from the Agència Tributària de Catalunya for Barcelona itself. Totals are shown before VAT so you can compare the rate schedules without arbitrarily applying the hotel tax treatment to every type of rental.
| Category in Barcelona | Regional component | Municipal component | Total before VAT per person and unit |
|---|---|---|---|
| Five-star, grand-luxury or equivalent hotel | €7 | €5 | €12 |
| Four-star or four-star superior hotel | €3.40 | €5 | €8.40 |
| Accommodation for tourist use | €4.50 | €5 | €9.50 |
| Youth hostel | €1 | €5 | €6 |
| Other campsites, establishments and facilities | €2 | €5 | €7 |
On small screens, scroll the table sideways.
An apartment for tourist use is therefore subject to a higher rate than a four-star hotel, before accounting for their respective VAT treatment. Star ratings do not place every category on a single scale: tourist accommodation has its own line. Conversely, a hostel may offer a private room while still falling under its regulated category.
The wording in a listing is therefore not enough. “Boutique,” “premium,” “residence” or “serviced apartment” describe a commercial offering; ask which category is used to calculate the tax. This is especially useful if two similar-looking properties show different taxes. You should be able to match the category used to the invoice and the information provided by the establishment.
VAT creates a second distinction. The ATC explains that the tax is included in the VAT tax base. The Spanish tax authority’s 2026 VAT table gives a rate of 10% for hotel services. Thus, €8.40 becomes €9.24 in our hotel example. For an apartment rental, ask how your contract is treated: we keep its rate here before VAT rather than automatically assigning it the rate for a hotel.
Three nights for two
Suppose two adults spend three consecutive nights at the same establishment, with no exemption and no prepayment that would qualify them for an earlier rate. That amounts to six taxable units. At a four-star hotel in Barcelona, the calculation comes to €50.40 before VAT, or €55.44 when the 10% hotel VAT applies. That is the total for the couple’s stay.
For the same people and length of stay, a five-star hotel comes to €72 before VAT, or €79.20 at this 10% rate. The tax difference between the two hotels is therefore €23.76 for the stay. This is in addition to the difference in room prices. If a room upgrade is offered at no extra charge per night, confirm the category actually being charged and whether the tax will differ.
For accommodation for tourist use, the rate comes to €57 before VAT. A youth hostel comes to €36, and the category of other establishments comes to €42, again before VAT. These figures compare the tax, not the full accommodation price. An apartment with a lower nightly rate may still have a lower total despite its higher tax rate; cleaning and service fees should also be included in the comparison.
To choose between two bookings, ask for a total for the same dates, the same travelers and the same services. Add accommodation, mandatory fees and any tax still due. Check the cancellation terms too: a slightly lower price with immediate payment and strict conditions may suit a trip with fixed plans, while a modifiable booking offers useful flexibility when dates are not settled.
This comparison works better on a single budget sheet than by looking at two advertised prices in separate browser tabs. Write down the final total for each offer and add a separate line for anything payable on site. This lets you distinguish the trip’s overall cost from the amount you will still need to pay when you arrive.
Families and groups
People aged 16 or under are exempt from this tax. From age 17, a traveler is included in the standard calculation unless another applicable exemption applies. For two adults and two children aged 10 and 15, the taxable portion of an identical hotel stay therefore remains that of the two adults. The price of the family room and any meals for the children are governed by the hotel’s commercial terms.
Proof of age matters. The ATC cites, among other documents, an identity card, passport or equivalent documents; it also provides declaration procedures for certain minors. When preparing for a family stay, bring the children’s usual identification documents and state their exact ages when booking. Simply giving the number of occupants may not always allow the property to calculate the tax correctly in advance.
For two adults and a 17-year-old staying four nights in a four-star hotel in Barcelona, the estimate is based on twelve units: €100.80 before VAT, or €110.88 with 10% VAT. Counting three taxpayers makes a significant difference compared with an estimate covering only the parents. If a birthday falls during the stay, ask the property to confirm the calculation for your specific case rather than applying an approximate age rule.
A group of friends should also calculate by person. Four adults in the same apartment for three nights amount to €114 in tax before VAT under the rates for tourist-use accommodation. Splitting this amount among the travelers when booking avoids leaving it out of the expense-sharing calculation. The number of rooms booked does not replace the number of people staying there.
Business trips are not generally exempt: the ATC’s FAQ makes this clear. Other situations may qualify for an exemption subject to conditions, including certain healthcare stays, social programs or force majeure cases. The required supporting documents must be provided. If you are visiting someone close to you or traveling for a reason that may be treated as a special case, ask about the applicable rule before counting on a saving in your budget.
The seven-unit cap
The taxable base is capped at seven units per person at the same establishment during one continuous period. For a full week in a four-star hotel in Barcelona, two adults therefore amount to €117.60 before VAT, or €129.36 with 10% VAT. The cap applies to the number of units, not to a flat amount that is identical across all categories.
For a longer continuous stay at the same hotel, the tax calculation therefore does not continue indefinitely beyond seven units per person. Accommodation prices, meals and other services naturally continue to follow the booking contract. This distinction is especially relevant to travelers staying in one place for ten days or so who are concerned that the tax will be multiplied across the entire stay.
Changing accommodation calls for a fresh calculation. The cap is tied to the same establishment and a continuous period; it is not a personal allowance of seven nights for an entire trip around Catalonia. If you split your stay between two hotels, each establishment applies the rules to the period you spend there. Give the property your full itinerary when requesting an estimate, especially if your booking is split across reservations.
Choosing a single base can therefore simplify luggage, formalities and budget tracking. Even so, tax alone should not determine your itinerary: an extra stop could bring you closer to an excursion or avoid a long return trip. Compare the total cost, including transport and the time available, rather than organizing your trip around the cap alone.
The bill and advance payment
The property collects the tax from travelers and reports it to the administration. For an ordinary stay, you therefore deal with your hotel or accommodation provider. The reporting deadlines listed on the ATC website apply to the professional; they do not require you to file a Catalan tax return for your weekend trip.
The timing of payment in practice depends on the booking terms: an amount may be collected in advance or remain due at the property. Ask a specific question: “For these travelers and these dates, what is the total tax still due, and is it shown with the applicable VAT?” Ask for a written response if the surcharge affects your choice between two places. Keep it with your booking confirmation.
An old booking does not automatically lock in an old rate. The ATC states that the rate in force when the booking was made may apply if the booking amount and the tax, including the municipal surcharge, were paid at that time. A deposit paid several months before arrival therefore does not, by itself, establish that the taxes have already been settled.
On the bill, the tax must be distinguished from the charge for services, with the number of units and the rate used. This detail helps explain an amount requested at reception: the people counted, the duration applied, the category and any VAT. If the tax already appears in an earlier payment, compare the supporting documents before paying it a second time.
If there is a discrepancy, first ask for the calculation rather than simply requesting a goodwill gesture. The difference may be due to a child being counted as an adult, a misunderstood category, an amount quoted before VAT, or a tax not included in the initial payment. An itemized charge is easier to correct than a dispute based solely on the total shown by a booking engine.
The municipalities around Barcelona
An address advertised as “near Barcelona” may be in another municipality. The tax distinction is based on the property’s actual location. To compare, note the full address and municipality name, then check the applicable rate. The neighborhood highlighted in an advert and its proximity to a point of interest are not enough to determine the amount.
Since October 1, 2026, several municipalities in the Barcelona area have applied their own surcharge: Castelldefels, Esplugues de Llobregat, L’Hospitalet de Llobregat, El Prat de Llobregat, Sabadell, Sant Cugat del Vallès and Sant Just Desvern. The assumption that the suburbs uniformly have no municipal surcharge is therefore no longer sufficient for correctly planning a stay in these municipalities.
In these seven municipalities, the ATC table gives a regional portion of €1.80 and a surcharge of €1.80 for four-star and four-star superior hotels during the period under consideration. The total is €3.60 before VAT per person and unit. For two adults and three nights, that amounts to €21.60 before VAT, or €23.76 with the 10% hotel VAT.
Compared with €55.44 for the same scenario in a four-star hotel in Barcelona, this represents a tax saving of €31.68 for the couple over the entire stay. This provides a concrete reference point. It should be weighed against the difference in room price, as well as the journeys you will actually make. No transport fare is assumed to be included in this saving.
An address outside the city may be suitable if it already fits your arrival, an appointment or a significant part of your itinerary. For three days focused mainly on central Barcelona, check connections, late-night return options and how easy it is to go back for a break. With children, these round trips may weigh more heavily in your choice than a tax difference spread over several days.
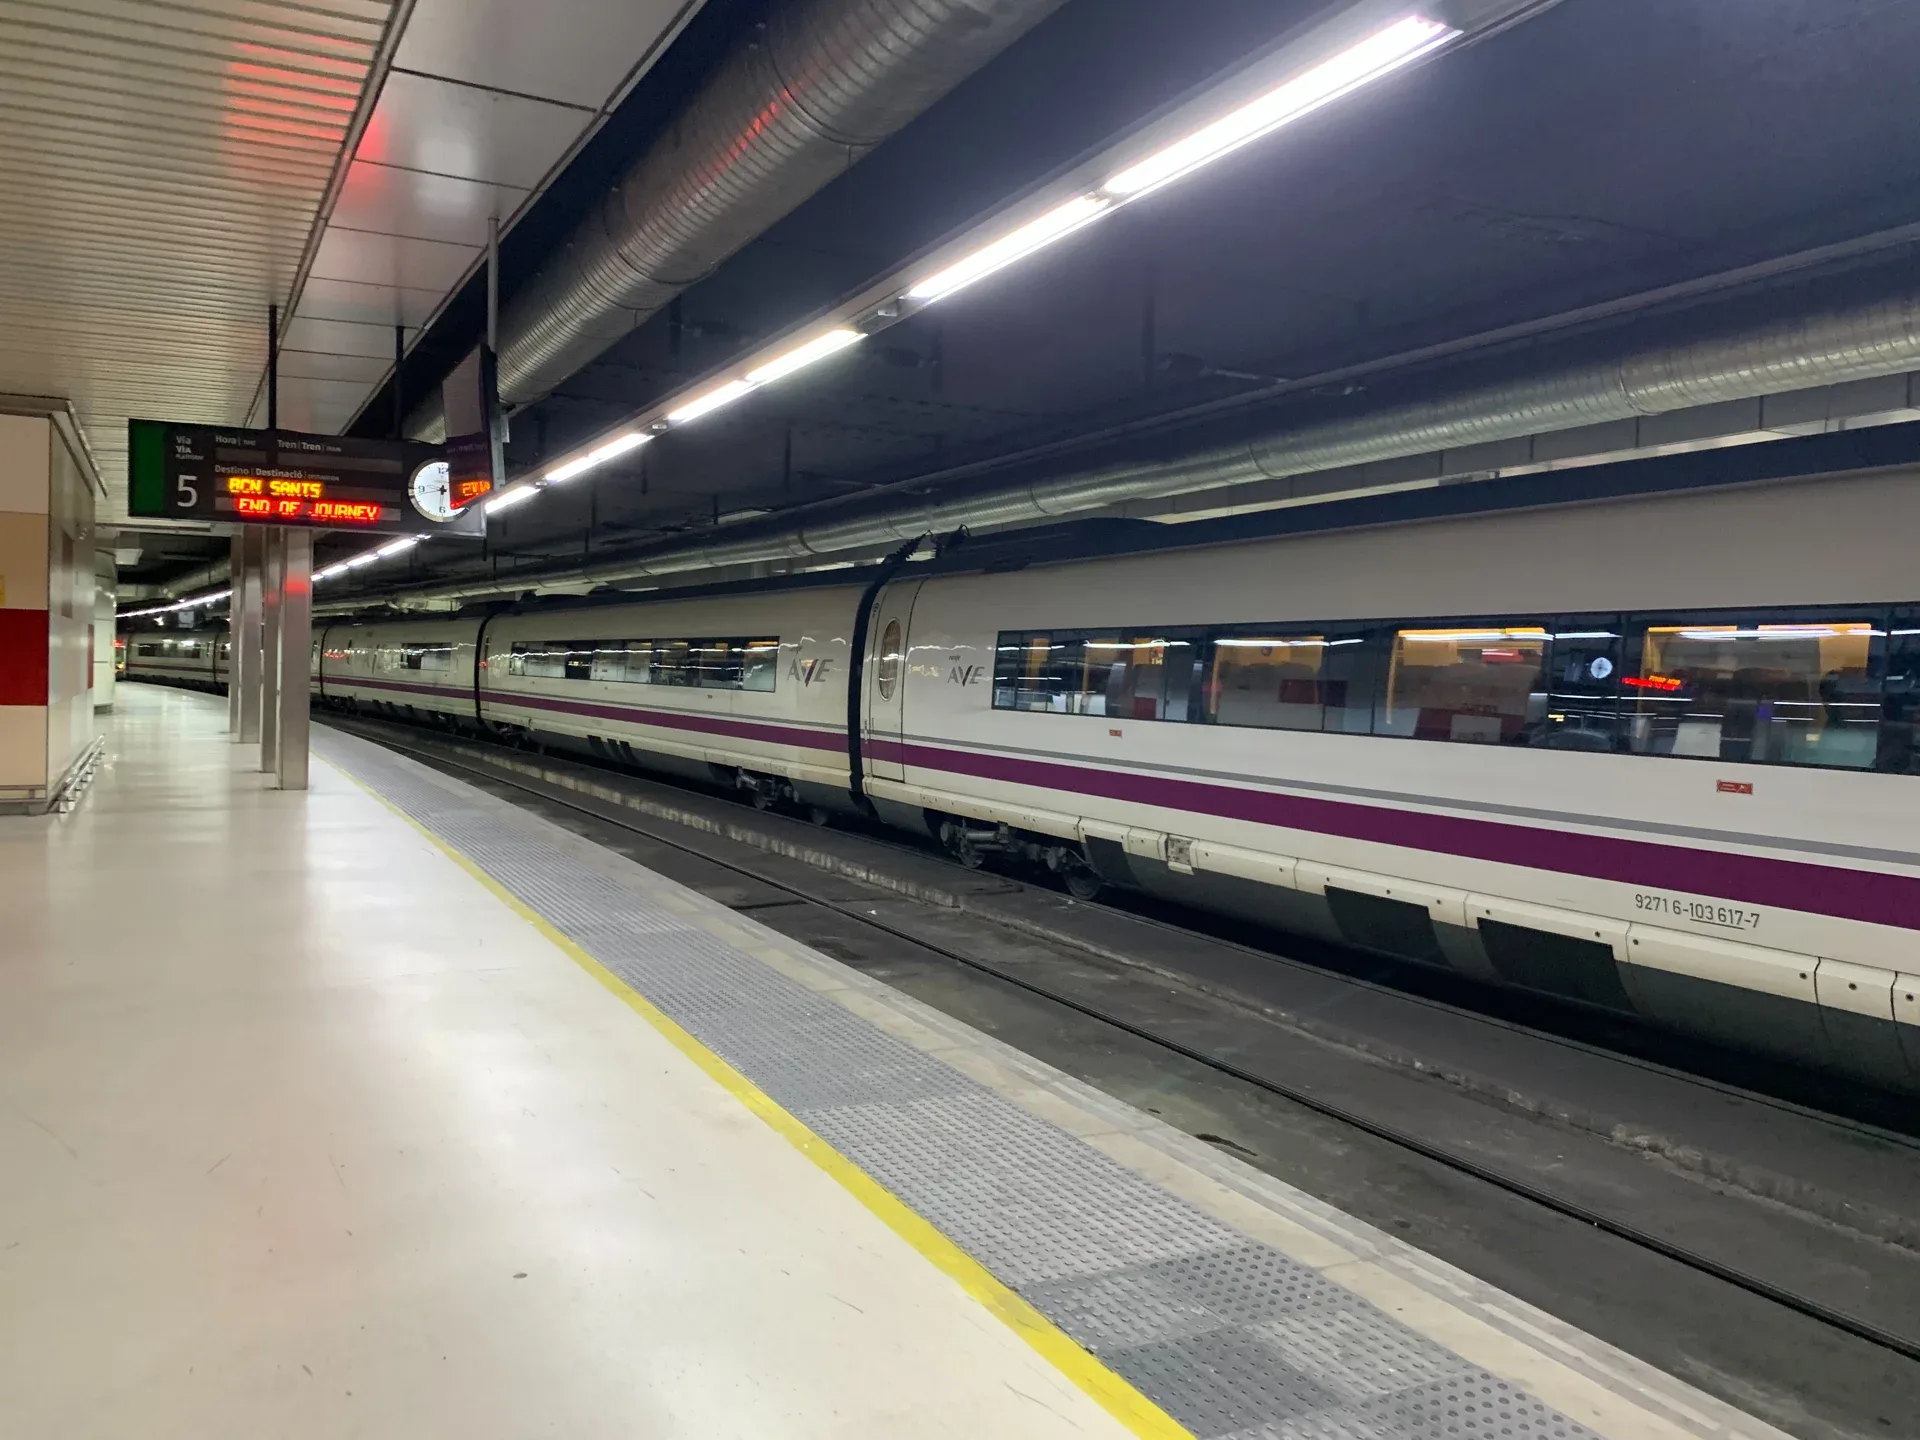
Barcelona-Sants station remains a useful landmark for planning a rail arrival, but its appearance on an itinerary does not tell you which municipality your hotel is in. The illustration shows an AVE train at a platform in Sants; plan your local transit separately, from the accommodation’s exact address to the places you intend to visit.

The total cost of accommodation and transport
A sample budget helps show the impact of these charges. Imagine two four-star hotels for two adults and three nights: the first in Barcelona at €120 per room per night, the second in one of the nearby municipalities mentioned at €110. These room rates are calculation assumptions and do not relate to an available offer. We assume they already include VAT on the room but exclude the tourist tax.
The first stay therefore comes to €360 for the room and €55.44 in tax including VAT, for a total of €415.44. The second comes to €330 for the room and €23.76 in tax including VAT, for a total of €353.76 before the additional travel costs. The difference available for those journeys is €61.68. That is the threshold to compare with the extra transport costs specific to your itinerary, for both travellers combined.
If, for this simulation only, you choose an additional travel budget of €36, the stay outside the city comes to €389.76. The final saving is €25.68. This budget is fictional: it does not represent an observed metro fare or taxi price. Replace it with the verified actual cost of the journeys that the out-of-town address adds to your trip.
The result helps you decide without prescribing the same answer for everyone. A final saving of a few dozen euros can matter when money is tight; a more suitable room, an easier return journey or the convenience of taking a break during the day may also justify choosing a central location. Finally, check that both options include the same meals and cancellation terms. A separately charged breakfast or mandatory fees missing from the advertised price will change the total independently of the tax rules.
Sightseeing budget
Once you have calculated the accommodation cost and its taxes, set aside a separate budget for activities. That way, you can choose a guided tour for the place that interests you most, then keep the rest of the day flexible. The tourist tax collected by the hotel is not a ticket to the monuments and does not replace any activity booking.
For a first introduction to the Sagrada Família with an English-speaking guide, we have selected a 90-minute tour that includes the basilica, the museum and access to the schools, as listed by the provider. The meeting point is Plaça de Gaudí. Group options distinguish between groups of up to 25 people and small groups of up to 15; a private tour in English is offered separately. Select the option you want when booking.
This format lets you make a single booking for an explanation of the monument while keeping the surrounding half-day relatively flexible. Allow time to travel from your accommodation and for the entrance checks; the tour starts at the meeting point, with no hotel transfer included. The provider’s dress code asks visitors to cover their shoulders and knees.
The starting price, rating and number of reviews appear on the offer’s main card, so there is only one place to update commercial information. These costs are added to your accommodation budget; no tax reduction applies to this tour. If you would rather explore without a guide, simply keep this budget for your own choice of ticket and time slot.

Viator
Sagrada Família: English-language group tour
To book one key tour after calculating your accommodation costs: 90 minutes at the Sagrada Família with an English-speaking guide, admission and museum included. Choose the group size and allow time to travel from your accommodation to Plaça de Gaudí.
- 1 hr 30 min
- 4.9/5 (2,283 reviews)
A 90-minute guided tour in English with admission and museum included. Group options for up to 25 or 15 participants; a separate private option in English. Meeting point: Plaça de Gaudí.
Cancellation policy
For a full refund, cancel at least 24 hours before the scheduled departure date.
From €54.00
View activityStays from April 2027 onward
For an arrival on or after 1 April 2027, recalculate using the rates for the relevant period. The ATC table already distinguishes several stages: in Barcelona, it shows a municipal surcharge of €6 for the period from 1 April 2027 to 31 March 2028, then €7 for the following period. The rates for late 2026 should therefore not be carried over mechanically into a spring quote.
The surrounding area requires the same care. The official tables show changes to the regional component and, depending on the municipality, the municipal surcharge from April 2027. A hotel that seems less expensive in tax for a November weekend may have a different total for your holiday dates. Ask them to specify the applicable period instead of simply asking for “the 2027 tax.”
For a trip booked well in advance, keep the itemised quote, payment terms and proof of any taxes already paid. These documents can be useful if the stay takes place after a rate change. They will help you distinguish a normal update to the outstanding balance from an amount already paid at the time of booking.
FAQ
Is the tourist tax included in the hotel price?
Your booking summary should make it clear whether the tax has been collected or is still due. A room-only price is not enough to determine this. Check the local tax line and ask for the outstanding amount for your group, including how VAT is handled. If you have prepaid, keep proof showing what was actually charged.
How much should two people budget for three nights in a four-star hotel?
In Barcelona, the rate schedule considered gives €8.40 before VAT per person and unit of stay for the period from 1 April 2026 to 31 March 2027. For two adults and three nights, that comes to €50.40 before VAT and €55.44 including hotel VAT at 10%. This calculation assumes an ordinary stay, with no exemption and no earlier rate applying to a fully prepaid booking.
Do children pay the tax in Barcelona?
People aged 16 or younger are exempt. From age 17, the standard rate applies unless another substantiated exemption applies. Provide the exact ages and have documents available to establish them. The terms for the room price, breakfast and tour tickets are separate from this tax exemption.
Is an apartment cheaper than a hotel in terms of taxes?
Tourist accommodation has its own rate: €9.50 before VAT per person and unit under the rate schedule shown. That is more than the €8.40 before VAT for a four-star hotel, but the total cost also depends on the accommodation price and its fees. Compare the final amounts and ask which VAT treatment actually applies to the rental.
Does the tax stop after seven nights?
The cap is seven units per person at the same establishment during a continuous period. It can therefore limit the taxable base for a longer stay at the same place. It is not a shared cap across all the hotels on a trip: if you change establishments, ask for the calculation for each leg. Other services are charged according to your booking.
Does staying in L’Hospitalet mean you avoid all tourist tax?
No. Since 1 October 2026, L’Hospitalet has applied a municipal surcharge in addition to the regional component. For a four-star hotel during the period considered, the total is €3.60 before VAT per person and unit. This is lower than the amount in Barcelona for this category, but you should compare the saving with the full accommodation price and transport costs for your stay.
Does a booking made before the increase keep its original rate?
The ATC provides for the rate in force at the time of booking to apply when the booking amount and the tax, including its surcharge, were paid at that time. So the fact that a booking was made earlier is not enough on its own. Check your proof of payment: a deposit, or a prepaid room with local taxes due on site, does not document the same situation.
Do you need to pay directly on a tax website before your trip?
For an ordinary hotel stay, the establishment collects the tax. Follow its payment instructions and request an itemised invoice. The professional is responsible for filing the declarations with the ATC. An activity ticket booked separately, even through a travel platform, does not settle the tax on your accommodation.
Sources and checks
Plan your visits and check current conditions.
- Rates and municipal surcharges
Agència Tributària de Catalunya · Accessed November 2, 2026
What this source supports
Barcelona: regional components and €5 surcharge from 01.04.2026 to 31.03.2027; nearby towns with surcharges since 01.10.2026; full prepayment; 2027 steps.
- French-language rate notice
Agència Tributària de Catalunya · Accessed November 2, 2026
What this source supports
Rates per person and unit; tax included in the VAT tax base.
- Overview of the tourist tax
Agència Tributària de Catalunya · Accessed November 2, 2026
What this source supports
Collection by accommodation providers, taxpayers, cap and exemptions.
- Taxable amount and cap
Agència Tributària de Catalunya · Accessed November 2, 2026
What this source supports
A maximum of seven units per person, at the same establishment, during a continuous period.
- Scope and exemptions
Agència Tributària de Catalunya · Accessed November 2, 2026
What this source supports
People aged 16 or under are exempt with proof; health, social services and force majeure subject to conditions.
- Billing and frequently asked questions
Agència Tributària de Catalunya · Accessed November 2, 2026
What this source supports
Separate invoice line showing units and rate; business stays are subject to the tax unless a specific exemption applies.
- 2026 VAT rates
Agencia Tributaria · Accessed November 2, 2026
What this source supports
Hotel services are subject to the reduced VAT rate of 10%. Apartment estimates remain before VAT.
- Sagrada Família: English-language guided tour
Viator / operator Crown Tours · Accessed November 2, 2026
What this source supports
Product 15932P95 active via Basic API; 90-minute duration, English-language guide, basilica, museum, schools, departure from Plaça de Gaudí; group sizes vary.
Viator — activity pages
Information about the offers featured in this article.Affiliate links: Odyvero may earn a commission when you book through this article’s buttons.
- Viator : Sagrada Família: English-language group tour
Accessed November 2, 2026


